09 July 2026
When it comes to managing debt, the feeling can often be overwhelming. But, fear not! There are strategies out there that can help you clear your debt efficiently and perhaps even make the journey a bit less daunting. Two of the most popular methods are the Debt Snowball and Debt Avalanche strategies. Ever heard of them? If not, you're about to find out how these approaches can help you say goodbye to your debts, possibly faster than you thought possible!Understanding the Basics: What Are These Strategies?
Before diving into the nitty-gritty, let's break down what each strategy entails.
Debt Snowball Method
Imagine you are building a snowman. You start with a small snowball and as you roll it through the snow, it picks up more snow, growing larger and larger. The Debt Snowball method works in a similar fashion. You start by focusing on your smallest debt, paying as much as you can on it while maintaining minimum payments on your other debts. Once the smallest debt is paid off, you move to the next smallest, rolling the previous payments into the new debt’s payments. This process creates a "snowball effect" as your available capital for paying off debt grows larger with each debt you eliminate.
Debt Avalanche Method
Now, picture an avalanche. It starts at the peak and rushes down, gaining momentum and power as it descends. The Debt Avalanche method involves paying off debts with the highest interest rates first, while still making minimum payments on other debts. By tackling the high-interest debts, you minimize the amount of interest you pay over time, which can save you money and speed up your debt repayment process.
Comparing Debt Snowball and Avalanche
Now that we understand what each strategy involves, let's delve deeper into their pros and cons.
Pros and Cons
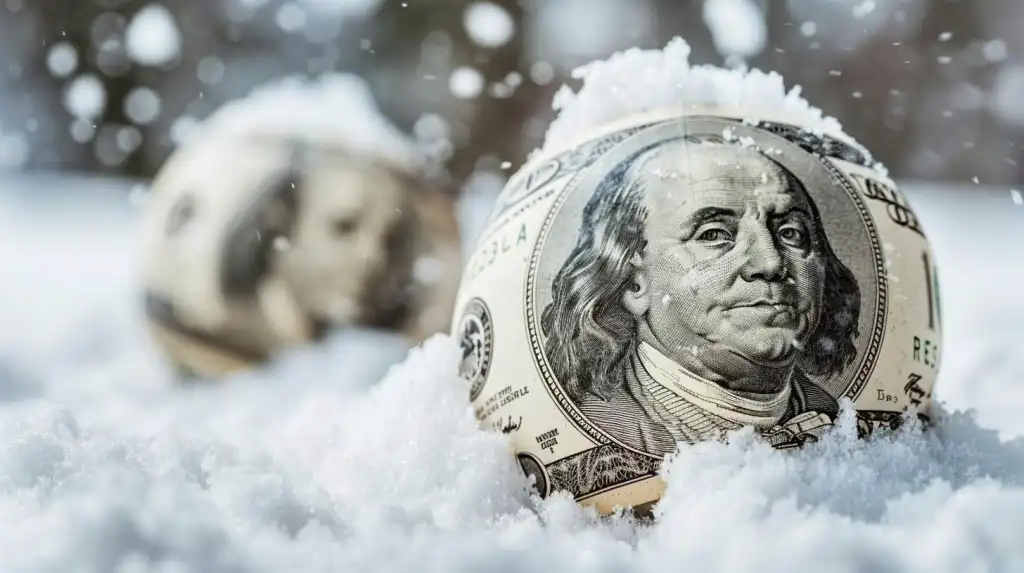
Debt Snowball
- Pros:- Quick Wins: Paying off smaller debts first can provide motivational boosts.
- Simple and Encouraging: Easy to keep track of progress.
- Cons:
- Potentially More Expensive: Since it doesn’t prioritize interest rates, total interest paid could be higher.
Debt Avalanche
- Pros:- Cost-Effective: Saves money on interest over time.
- Efficient: Targets the most financially draining debts first.
- Cons:
- Requires Patience: Larger debts can take longer to pay off, which might affect motivation.
Which Method Should You Choose? Choosing the right method depends on your personal financial situation and your psychological needs. Ask yourself: What’s more important to you, saving money on interest or feeling motivated by quick wins?
When to Choose Debt Snowball
If you’re someone who gains momentum from small victories, then the Debt Snowball might be your best bet. It’s particularly effective if you have several small debts and need the psychological wins to keep going.When to Use Debt Avalanche
If you’re focused on the long-term financial picture and are less concerned about short-term wins, then the Debt Avalanche method could be more suitable. It’s ideal for those who have high-interest debts and are disciplined enough to stick with the plan even if the immediate results are not visible.Real-Life Application: How to Implement Your Chosen Strategy 1. List Your Debts: Write down all your debts, including amounts and interest rates.
2. Budget Wisely: Ensure you have a realistic budget that prioritizes your debt repayment.3. Choose Your Strategy: Based on your financial assessment and personal preference, select either the Snowball or Avalanche method.
4. Stay Consistent: Whichever method you choose, consistency is key. Stick to your payments and adjust your budget if needed.
5. Celebrate Milestones: Whether it’s paying off a debt or reaching a financial goal, celebrate. It helps keep the motivation alive!
Conclusion: Tailor Your Debt Repayment to Your Needs Both the Debt Snowball and Avalanche methods have their merits, and the best choice depends on your individual circumstances and psychological makeup. Do you revel in quick wins, or do you prefer a more calculated approach to minimizing interest over time? Remember, the goal is not just to pay off debt, but to do so in a way that is manageable and aligned with your financial goals.
So, which will it be for you, the snowball or the avalanche? Whichever you choose, you're taking a step in the right direction towards financial freedom. Remember, the journey of a thousand miles begins with a single step. Ready to take yours?